Governments Urged to Unlock Private Investment for Climate Resilience
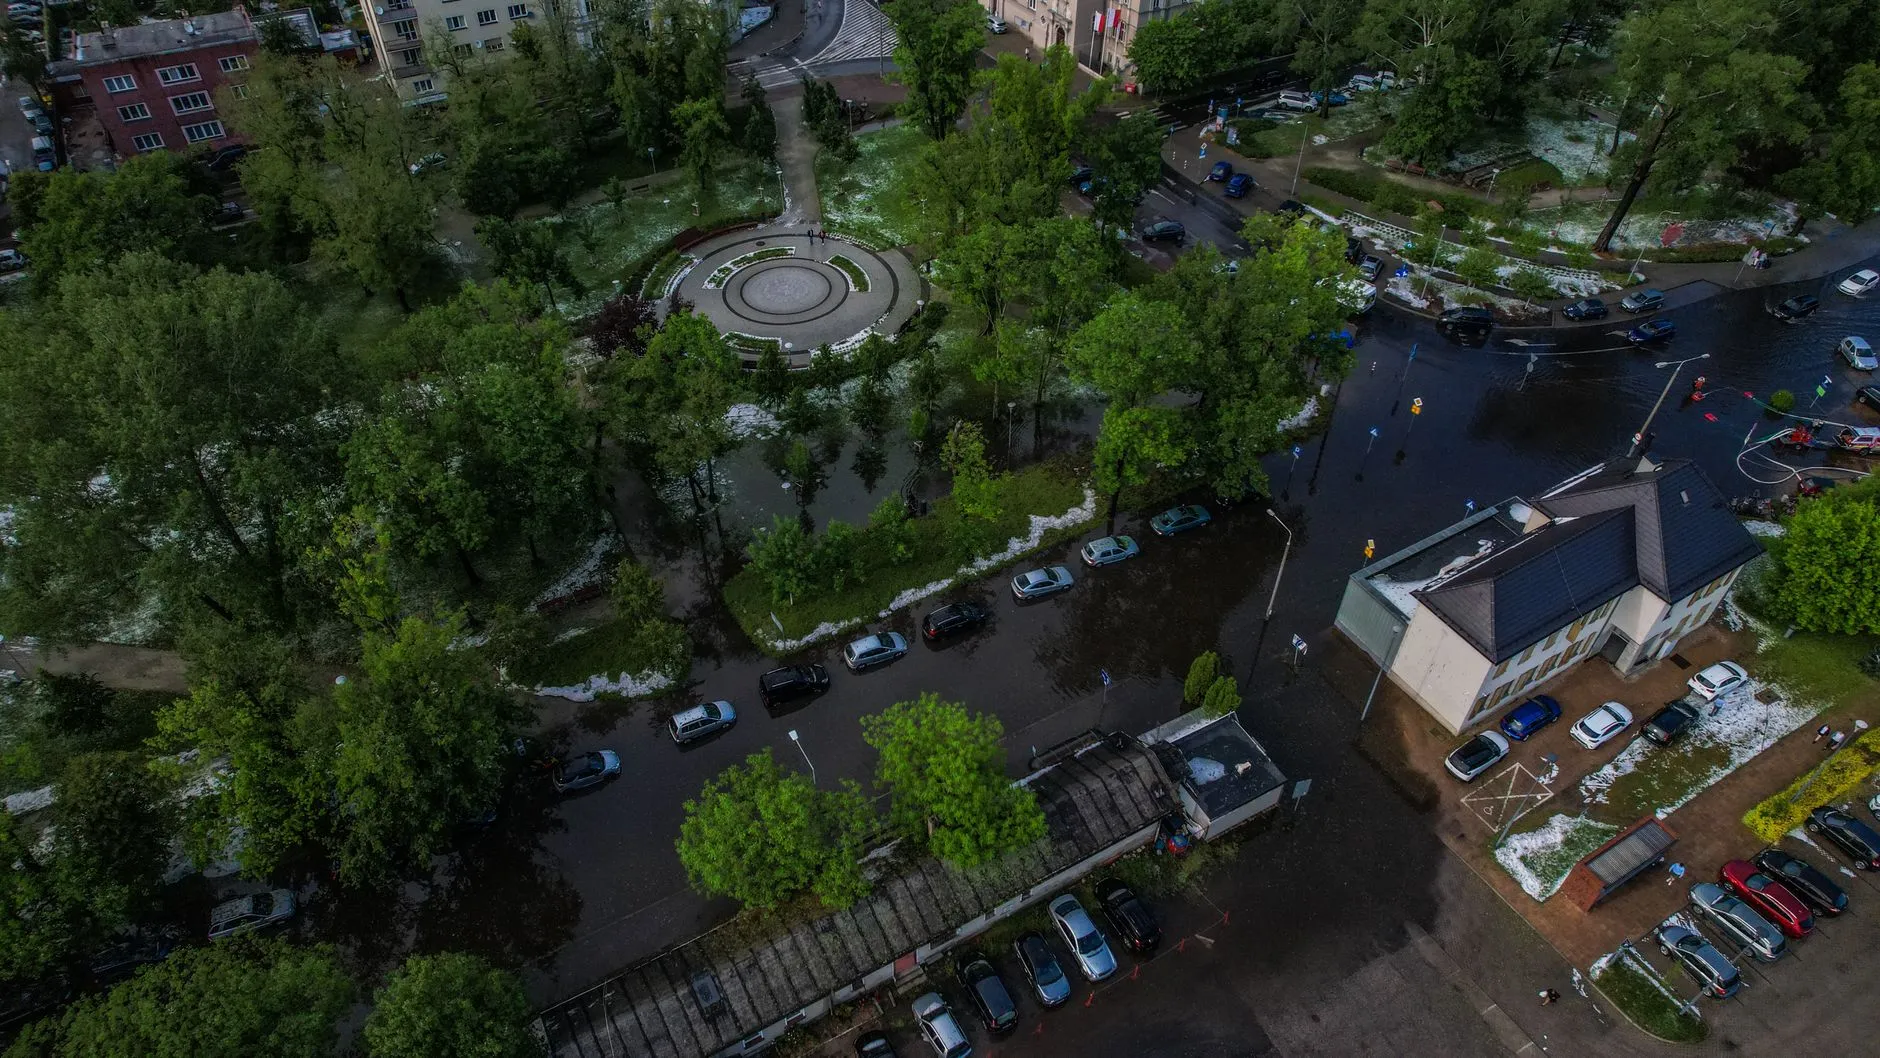
Extreme weather damage is forcing Europe to confront a stark financial reality. New figures suggest the continent faces a €500 billion bill for climate resilience through 2035, representing a fundamental shift in how governments must plan public spending. Rather than treating flood defences, storm repairs, and infrastructure upgrades as emergency responses, analysis now frames them as a continuous investment cycle that will define public budgets for the next decade.
This matters because the sums involved are too large for public finance alone. Consequently, governments will need to create conditions that allow pension funds, insurers, and infrastructure investors to participate. For UK businesses, particularly those in construction, engineering, and supply chains serving public infrastructure, this represents a sustained order book. However, it also means adapting to new procurement requirements, climate risk standards, and collaboration models between public and private sectors.
The estimates were released during Climate Week NYC in September 2024, where policy groups emphasised that adaptation finance remains seriously underfunded compared to the scale of climate impacts already visible across Europe. The Taskforce on Net Zero Policy argued that resilience must be embedded into transition plans and national investment strategies, not treated as separate from decarbonisation efforts. Moreover, the group warned that without clearer frameworks, private capital will remain on the sidelines while costs continue to rise.
Spending projections show rapid escalation from 2026 onward
Bloomberg Intelligence published its analysis on 23 September 2024, estimating that EU and UK governments are on track to spend €28.7 billion on climate adaptation and disaster reconstruction in 2026. That figure is projected to climb steeply, reaching approximately €80 billion annually by 2035. Cumulative spending over the period totals around €500 billion.
The analysis highlights a notable trend. Spending on rebuilding and adaptation across the EU and UK has more than doubled in each five year period since 2011. What had previously been categorised as isolated disaster repair is now described as a sustained investment cycle, driven by the rising frequency and cost of extreme weather events.
These figures cover two distinct but related categories. First, post disaster reconstruction following floods, storms, and heatwaves. Second, proactive resilience measures such as upgraded drainage systems, coastal defences, and heat resistant infrastructure. Both categories are growing, and governments are beginning to plan for them as recurring rather than exceptional costs.
The European Commission has separately estimated that the EU needs roughly €70 billion per year in climate adaptation investment through 2050. The UK Climate Change Committee has put the comparable figure for the UK at £11 billion annually. Bloomberg Intelligence's €500 billion estimate is higher because it includes both EU and UK spending through 2035, combining reactive repair work with forward looking resilience measures.
These projections reflect a changing risk landscape. Extreme weather events that were once considered rare are now occurring with greater frequency. As a result, governments are shifting from ad hoc emergency spending to planned, multi year infrastructure programmes designed to reduce future losses.
Policy context emphasises need for private sector involvement
The Taskforce on Net Zero Policy is a multi stakeholder initiative focused on accelerating credible climate policy, including resilience measures alongside carbon reduction. Its current work stresses that adaptation finance is "dangerously off-track" and that governments must create conditions for private investment to flow at scale.
The taskforce argues that resilience should be integrated into transition plans, risk assessments, and regional investment strategies. This reflects a broader recognition that adaptation cannot be separated from mitigation. For example, retrofitting buildings to improve energy efficiency also makes them more resilient to heatwaves. Similarly, flood defences that protect power infrastructure support both climate goals and energy security.
European Commission documents on climate resilience financing echo this message. The Commission states that Europe must "decisively scale up investments in climate adaptation and resilience, both by the public and private sectors." Nevertheless, turning that ambition into bankable projects requires clearer regulatory frameworks, standardised risk assessments, and financial instruments that reduce investor uncertainty.
Public budgets alone cannot meet the scale of investment required. Therefore, governments are exploring blended finance models, green bonds, and public guarantees designed to attract institutional capital. However, private investors typically require predictable returns, transparent procurement processes, and long term policy certainty. Without these conditions, capital will flow to other asset classes with lower perceived risk.
The policy challenge is compounded by the fact that adaptation projects often deliver diffuse benefits over long timescales, making them harder to finance than revenue generating infrastructure such as toll roads or energy projects. Consequently, public sector involvement will remain essential, both to fund projects with primarily social benefits and to de risk investments that can attract private co-financing.
Construction, engineering, and supply chain impacts for UK firms
For UK businesses in construction, civil engineering, and related supply chains, the shift to sustained resilience investment creates both opportunities and obligations. Companies tendering for public infrastructure projects can expect climate adaptation to feature more prominently in procurement criteria. Consequently, demonstrating relevant experience, technical capability, and carbon credentials will become increasingly important.
Local authorities are already integrating climate resilience into capital programmes. Flood defence schemes, sustainable drainage systems, and transport infrastructure upgrades are moving from reactive repairs to planned, long term programmes. This creates a more stable pipeline of work, but also raises the bar for suppliers. Contracting authorities are likely to favour firms that can demonstrate understanding of climate risk, whole life carbon assessment, and nature based solutions.
Insurance considerations are also shifting. Businesses operating in flood risk areas or exposed to extreme weather may face higher premiums or more stringent underwriting requirements. Therefore, investing in site level resilience measures, such as improved drainage, heat management, or supply chain diversification, may become a commercial necessity rather than a voluntary choice.
Manufacturers and material suppliers should anticipate growing demand for resilience related products. These include permeable paving, flood resistant building materials, heat reflective coatings, and climate adapted infrastructure components. However, public procurement frameworks are also tightening around embodied carbon and circular economy principles. As a result, suppliers will need to provide transparent environmental data and consider product life cycle impacts.
Professional services firms, including architects, engineers, and project managers, are likely to see increased demand for climate risk assessment, adaptation planning, and retrofit design. Public sector clients are embedding resilience requirements into project briefs, and firms without relevant expertise may find themselves excluded from tender processes. Training staff and developing in house knowledge will therefore be important for maintaining competitiveness.
Supply chain resilience is another commercial factor. Extreme weather disrupts logistics, damages facilities, and delays projects. Businesses that map climate risks across their supply networks and develop contingency plans will be better positioned to maintain service continuity. This is particularly relevant for firms operating just in time delivery models or relying on single source suppliers in vulnerable regions.
What UK businesses should focus on now
- Europe faces a projected €500 billion climate resilience spending requirement through 2035, with annual costs rising from €28.7 billion in 2026 to approximately €80 billion by 2035.
- Spending has more than doubled in each five year period since 2011, reflecting the shift from isolated disaster repairs to continuous investment cycles.
- The European Commission estimates the EU needs around €70 billion annually for adaptation through 2050, while the UK Climate Change Committee puts the UK figure at £11 billion per year.
- Policy groups including the Taskforce on Net Zero Policy warn that adaptation finance is seriously underfunded and that private sector participation is essential to close the gap.
- Governments are exploring blended finance models, green bonds, and public guarantees to attract institutional investment, but require clearer regulatory frameworks and standardised risk assessments.
- Businesses in construction, engineering, and infrastructure supply chains can expect resilience criteria to feature more prominently in public procurement, alongside carbon reduction and circular economy requirements.
- Insurance costs and underwriting conditions are tightening for firms in high risk areas, making site level resilience measures increasingly important for commercial viability.
Preparing for stricter procurement and reporting standards
The shift toward planned resilience investment will change how public contracts are structured and evaluated. UK businesses should review their capability to respond to tenders that include climate adaptation requirements. This includes understanding flood risk mapping, nature based solutions, and climate scenario analysis. Firms that can demonstrate these competencies will have a competitive advantage as local authorities and government departments expand resilience programmes.
Carbon reporting is also tightening. Public procurement frameworks such as PPN 06/21 already require suppliers to publish carbon reduction plans when bidding for contracts above certain thresholds. Our net zero program for carbon reporting compliance helps businesses meet these requirements and prepare for future regulatory tightening. As adaptation spending scales up, procurement authorities are likely to link resilience objectives with carbon reduction targets, requiring suppliers to address both simultaneously.
Training is another practical consideration. The skills required to deliver climate resilient infrastructure differ from traditional construction and engineering practices. Businesses may need to upskill staff in areas such as climate risk assessment, green infrastructure design, and sustainable materials specification. Resources through the SBS Academy can support teams in developing relevant knowledge and staying current with evolving standards.
Financial planning should also account for potential shifts in capital allocation. If government spending on resilience increases as projected, budgets for other infrastructure categories may be squeezed. Businesses relying on public sector contracts should diversify their client base and consider how climate adaptation creates new market opportunities across both public and private sectors.
Collaboration will become more important. Large scale resilience projects often involve multiple contractors, consultants, and public agencies working together over extended timescales. Firms that can demonstrate effective partnership working, transparent communication, and alignment with public policy goals will be better positioned to secure and deliver major contracts.
Finally, businesses should monitor policy developments closely. The regulatory landscape for climate resilience is evolving rapidly, with new standards, funding mechanisms, and reporting requirements emerging at both UK and EU levels. Staying informed and engaging with industry bodies will help firms anticipate changes and adapt their operations accordingly.
Where to find authoritative guidance and data
The UK government's climate adaptation resources are available through the Department for Energy Security and Net Zero, which publishes policy updates, funding announcements, and technical guidance. The department oversees the UK's approach to both mitigation and adaptation, providing a central reference point for businesses seeking to understand government priorities.
The UK Climate Change Committee provides independent analysis on climate risk and resilience, including detailed assessments of adaptation funding requirements and progress against national targets. Its reports offer evidence based recommendations that inform government policy and can help businesses anticipate regulatory direction.
For European policy context, the European Commission's climate adaptation pages set out the EU's strategy for scaling resilience investment. Although the UK is no longer part of the EU, many UK businesses operate across European markets or participate in supply chains serving EU infrastructure projects. Understanding EU policy therefore remains commercially relevant.
The Taskforce on Net Zero Policy, convened by the Principles for Responsible Investment, brings together investors, policymakers, and industry experts to develop credible climate policy frameworks. Its work on adaptation finance and resilience provides insight into how institutional investors are assessing climate risk and what conditions are needed to mobilise private capital at scale.